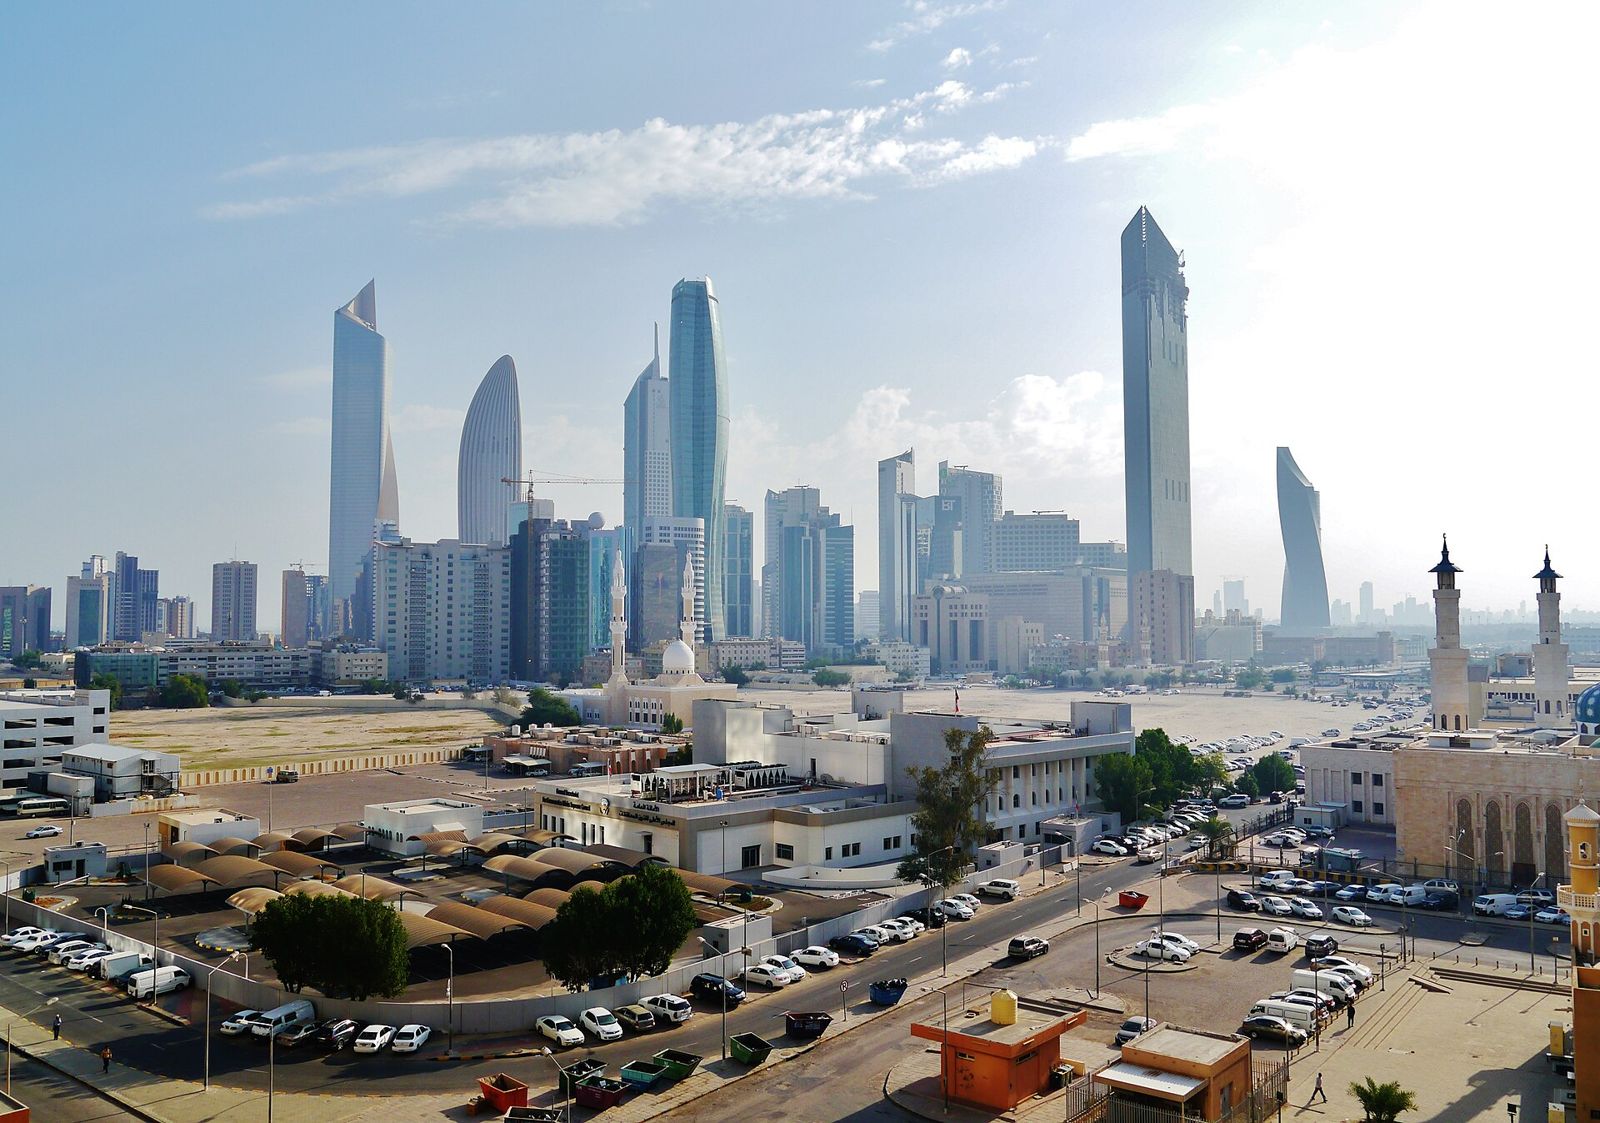
 Photo: Zairon / Wikimedia Commons (CC BY 4.0)
24 August 2026 ·3 min read
Branded Residences in Kuwait: Domestic Wealth, Closed Market

Most market reports treat Kuwait as a minor Gulf entry and move on. For anyone selling branded residences in the region, that is a serious oversight. Kuwaiti family offices and high-net-worth households are among the most consistent buyers of prime branded product in London, Dubai, Egypt's North Coast, Marbella and the Mediterranean. Understanding Kuwait matters less for what you can build there and more for who you are selling to elsewhere.
The domestic constraint
Foreign ownership of real estate in Kuwait is tightly restricted, with limited exceptions and a regulatory environment that has historically been cautious about opening the sector. GCC nationals have somewhat broader access than other foreign buyers, but nothing approaching the freehold regimes of the UAE, Bahrain or Oman.
The practical effect is that a branded residential scheme in Kuwait is selling almost entirely to Kuwaitis and, to a limited degree, other GCC nationals. That is not a trivial market — Kuwaiti purchasing power is substantial — but it is a finite one, and it caps scheme scale and pricing headroom.
What works domestically
- Urban hospitality-branded apartments in the Kuwait City / Salmiya corridor, aimed at Kuwaiti households seeking serviced convenience and a managed building.
- Managed sea-front product, where the scarcity of quality waterfront stock supports a genuine premium.
- Serviced branded product for the returning diaspora and senior professionals.
What does not work is large-scale resort branded product. Kuwait's climate, coastline and leisure infrastructure do not support it, and the domestic buyer with resort intent buys in Dubai, Bahrain, Egypt or the Mediterranean instead.
Kuwait as a buyer pool — the more important story
For developers building branded residences anywhere from Cairo to Marbella, Kuwaiti demand has distinctive characteristics worth designing for.
| Characteristic | Implication for your scheme |
|---|---|
| Large multi-generational households | Demand skews to four-bedroom-plus and lateral layouts |
| Strong privacy expectations | Separate family and majlis entertaining zones; discreet access |
| Summer-escape seasonality | Peak occupancy June-September in Mediterranean and European markets |
| Conservative, relationship-led purchasing | Long lead times; trusted intermediaries matter more than advertising |
| Preference for established brands | Recognition outweighs novelty; unknown labels struggle |
Schemes that ignore these — a three-bedroom-dominant unit mix, open-plan-only layouts, no privacy sequencing — systematically underperform with this buyer pool despite strong headline demand for the location.
Kuwait as a capital source
Kuwaiti sovereign and family office capital has a long history in international real estate, with a bias towards income-producing assets, established jurisdictions and long holding periods. For a sponsor seeking equity or a JV partner for a hospitality or branded residential scheme, this is a genuinely relevant pool — but it is patient, diligence-heavy and relationship-driven. It does not respond to a teaser and a deadline.
Pitfalls
- Assuming a UAE-style freehold structure is available. It is not.
- Over-scaling a domestic scheme against a finite domestic buyer pool.
- Designing for Kuwaiti buyers abroad without accommodating household size and privacy expectations.
- Approaching Kuwaiti capital transactionally rather than through established relationships.
Outlook
Kuwait's domestic branded pipeline will stay modest, constrained by the ownership regime rather than by wealth. Its significance to the branded residence industry lies in the other direction: as a buyer pool and capital source that rewards developers who understand what Kuwaiti households actually want from a home. That understanding is worth more than a market-entry study.
Frequently Asked Questions
Can foreigners buy property in Kuwait?
Foreign ownership of Kuwaiti real estate is tightly restricted, with limited exceptions. GCC nationals have somewhat broader access than other foreign buyers, but nothing comparable to the freehold regimes of the UAE, Bahrain or Oman. Confirm the current statutory position with Kuwaiti counsel before structuring any transaction.
Are there branded residences in Kuwait?
Yes, but the domestic market is small and concentrated in urban hospitality-branded apartments in the Kuwait City and Salmiya corridor and in scarce waterfront product. Large-scale resort branded product does not work domestically; Kuwaiti buyers with resort intent purchase in Dubai, Bahrain, Egypt or the Mediterranean.
Why does Kuwait matter to branded residence developers elsewhere?
Kuwaiti households and family offices are among the most consistent buyers of prime branded product in London, Dubai, Egypt's North Coast and the Mediterranean, and Kuwaiti institutional capital is an established source of real estate equity. Designing unit mix and privacy sequencing for this buyer materially improves absorption in those markets.
What do Kuwaiti buyers look for in a branded residence?
Larger lateral layouts suited to multi-generational households, clear separation between family and entertaining zones, discreet access and strong privacy, established and recognised brands rather than novel ones, and a relationship-led sales process with realistic lead times.
See also
Market guides by country
- 'The Future of Branded Residences' — Global Tour 2026
- What Are Branded Residences? The Definitive 2026 Guide
- Branded Residence Ownership Structures Explained: The 2026 Guide
- Hotel-Branded vs Design-Branded Residences: The 2026 Comparison
- What Are Branded Residences? 2026 Definition, Models and Market Size