 Photo: Elie Saab Residences Cairo — Brand Atlas
9 October 2026 ·4 min read
Branded Residences in Cairo 2026: New Cairo, Sheikh Zayed and the New Capital
Few markets show how the branded residence model adapts to local conditions better than Cairo. Here, the brand is not mainly a tourism story. It is a trust and differentiation story in a city where gated compounds compete intensely for the same buyers, and where purchasers want reassurance that what they buy off-plan will be delivered, maintained and resaleable.
Where the branded supply sits
- New Cairo and the Fifth Settlement — the largest concentration of premium compounds. Branded villas, townhouses and apartments within master-planned communities, often with a hotel or club component.
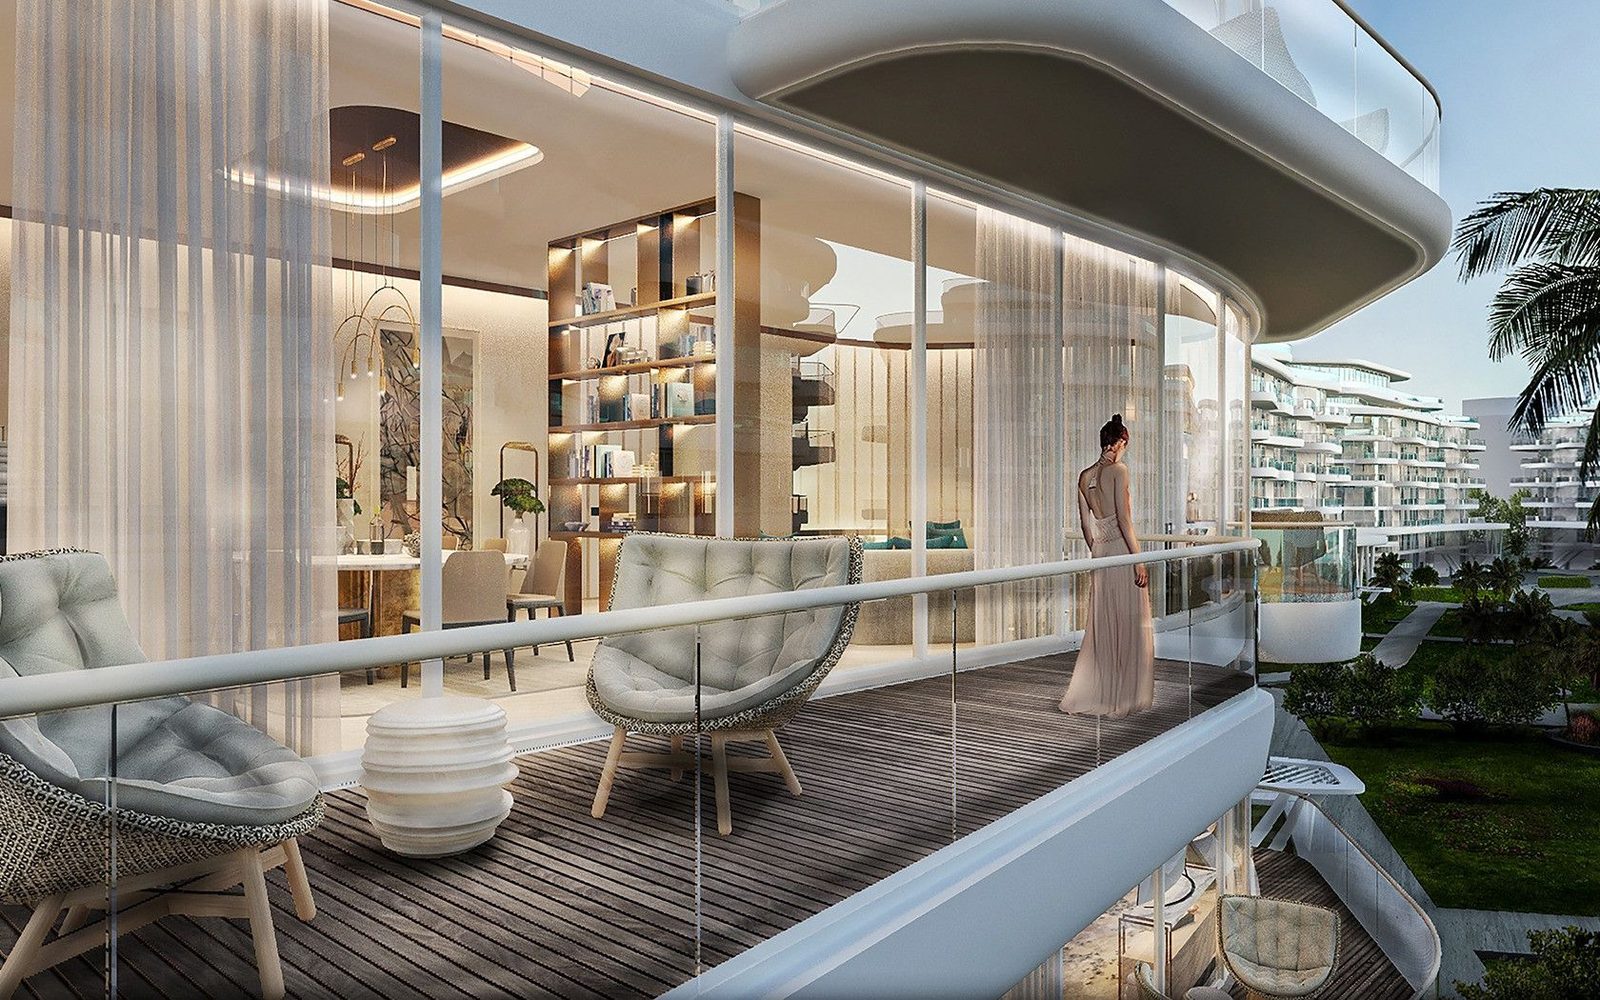
- Sheikh Zayed and West Cairo (6th of October) — the western counterpart, popular with families and with fashion-branded compounds. Elie Saab's Cairo residences are a prominent example of the fashion-branded model applied to a landscaped compound.
- The Nile corridor (Zamalek, Garden City, Maadi, the Corniche) — the rare city-centre waterfront product. Hotel-attached towers with river views and very limited land.
- The New Administrative Capital — government-led new city east of Cairo, with mixed-use towers and hotel-branded residences in the Central Business District. Longer horizon, higher execution risk, and strong government backing.
Why the brand works in Cairo
Egyptian buyers have learned to discount developer promises. Payment plans of 7 to 10 years are common, which means the buyer is effectively lending to the developer for most of the construction period. A brand's presence signals that a third party with a global reputation has reviewed the scheme and is willing to stand behind the delivered product.
The brand also solves a later problem: maintenance and facility management. Many older compounds have aged badly. An operator-managed branded community promises to stay at standard, which supports resale values.
| Area | Typical branded product | Indicative premium vs comparable unbranded |
|---|---|---|
| New Cairo | Hotel- or fashion-branded compound units | 15-30% |
| Sheikh Zayed / West Cairo | Fashion-branded villas and apartments | 15-30% |
| Nile corridor | Hotel-attached towers | 25-40% |
| New Administrative Capital | CBD hotel residences | 10-25% |
The pound and the payment plan
The Egyptian pound lost more than half its value against the dollar between 2022 and early 2024, culminating in the March 2024 float. That episode explains the market. Egyptians bought property — branded and unbranded — as a store of value, and developers raised prices repeatedly.
The large Gulf investment that followed, most visibly the Ras El Hekma agreement with Abu Dhabi's ADQ on the North Coast, improved foreign currency availability and confidence. For branded schemes, the result is a market where:
- Local buyers pay in pounds over long payment plans.
- Expatriate Egyptians and foreign buyers increasingly pay in dollars, sometimes with discounts.
- Developers carry construction-cost inflation risk against prices locked years earlier.
That last point is the critical one for underwriting. A brand cannot fix a payment-plan structure that does not cover future construction costs.
Brand selection in the Cairo context
- Fashion and design brands work well in large compounds where the brand can shape landscape, clubhouses and interiors without requiring a full hotel.
- Luxury hotel brands are best suited to the Nile corridor and to schemes with a genuine hotel component.
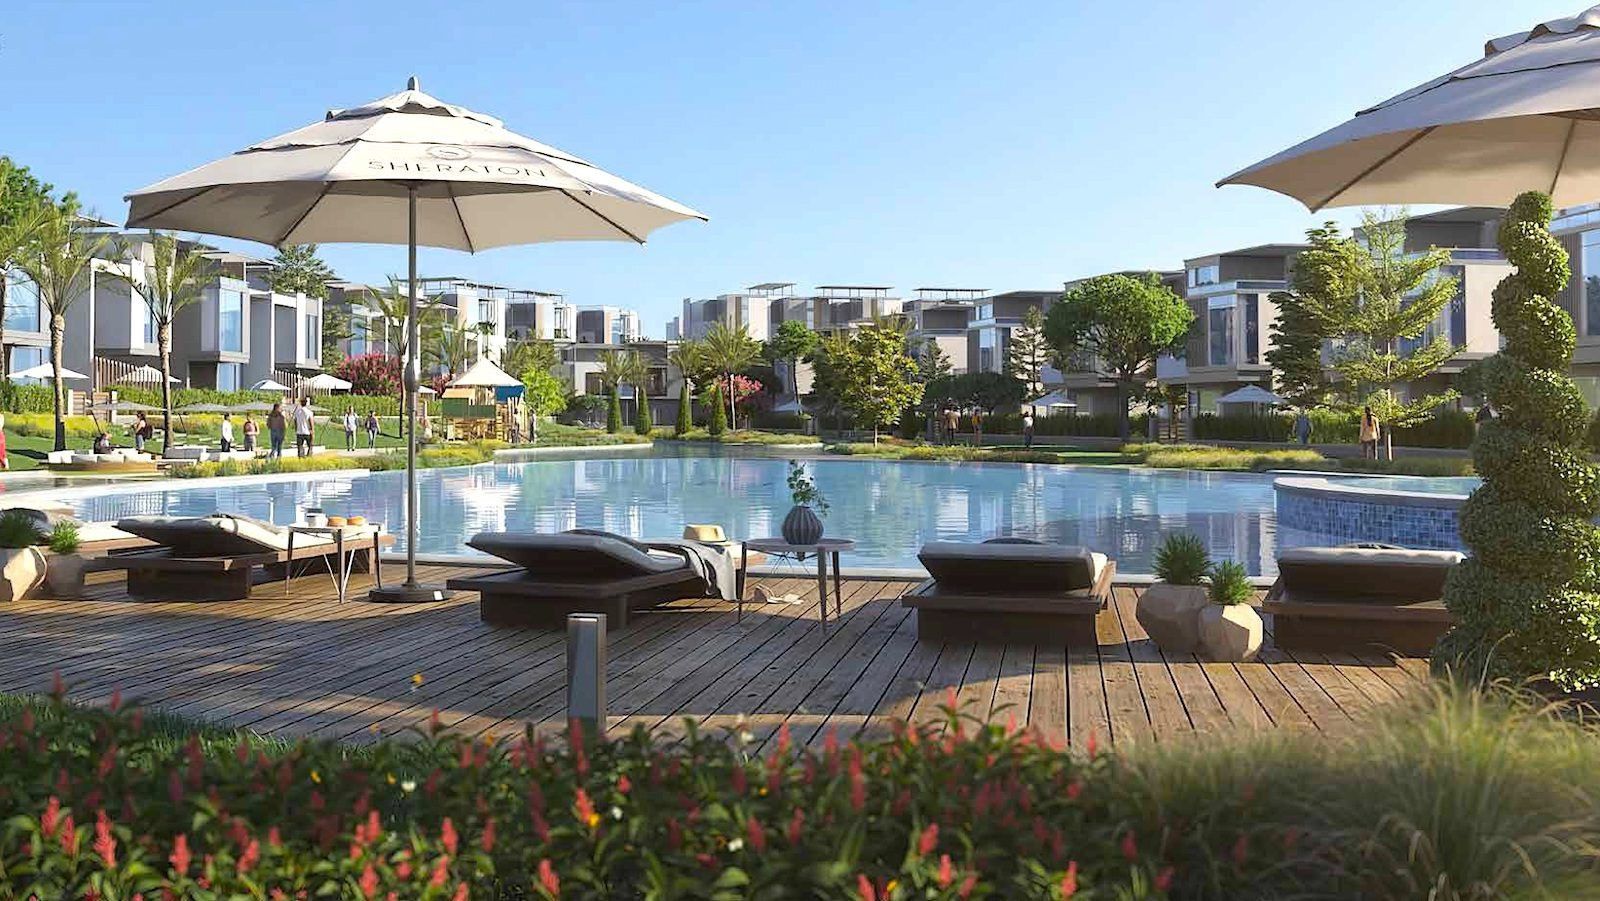
- Upper-upscale brands (Sheraton, Marriott and similar) are a strong fit for larger-volume compounds and the New Capital, where a credible operator at sensible fees matters more than prestige.
Matching brand tier to site and buyer is the single biggest determinant of whether the premium covers the licence fee and operating standards.
Sponsor pitfalls
- Brand standards vs. payment plans. Brand standards raise costs; long payment plans fix prices. Model both together.
- Operator obligations post-handover. Define service charge levels and reserve funds early — Egyptian buyers are sensitive to future charges.
- Delivery delays. Brands increasingly include termination rights for late delivery. Know your exposure.
- Dollar-pricing compliance. Rules around foreign-currency pricing have tightened; structure sales with local counsel.
Outlook
Cairo will continue to be one of the most active branded residence markets outside the Gulf. We expect more fashion and lifestyle brands in compounds, more hotel-branded towers along the Nile and in the New Capital, and growing interest from Gulf developers partnering with Egyptian landowners. The schemes that succeed will be those that pair a credible brand with a realistic payment structure and a strong delivery record.
Frequently Asked Questions
Where are the branded residences in Cairo?
Mainly in New Cairo and the Fifth Settlement, Sheikh Zayed and West Cairo, along the Nile corridor, and in the New Administrative Capital's business district.
Which brands have residences in Cairo?
Active brands include fashion houses such as Elie Saab and hotel brands such as W, Sheraton, Marriott, Four Seasons and Ritz-Carlton, typically in partnership with Egyptian developers.
Are branded residences in Cairo a good hedge against devaluation?
Egyptian buyers have used property, including branded residences, as a store of value during pound devaluation. Value depends on location, delivery and the developer's ability to complete at the agreed standard.
See also
Capital, M&A & asset sales
- Branded Residences Market Report — GCC Edition 2026
- Branded Residence Ownership Structures Explained: The 2026 Guide
- Hotel-Branded vs Design-Branded Residences: The 2026 Comparison
- What Are Branded Residences? 2026 Definition, Models and Market Size
- Trustworthy Branded Residence Brands in 2026: How to Judge Credibility